Post-colonial exploitation is still dominating world trade
Of raw coffee prices and 'paper coffee'
Mechanisms and problems of conventional coffee trade
Second only to mineral oil, coffee is one of the most important trade goods on earth. About 100 million people are working in the worldwide coffee business. They work in cultivation, processing, and trade. 25 million small-scale farmers' family units produce 80% of coffee, with less than 10 hectares of land. Many of them are subsisting on less than 2 dollars a day and are threatened by price fluctuations, resulting in poverty and hunger.[1] Famines have been triggered by plummeting raw coffee prices.
Of the more than 150 million sacks harvested on average each year, about 70% are exported. Ca. 1,14 million tons are imported to Germany every year. Typically, the coffee is processed locally and resold internationally. Germany is the world's biggest exporter of coffee products, despite not having a single coffee plant in the country![2]
Redistribution from bottom to top: Who gets the money?
The figure below shows that only a small share of a cup of coffee goes to the workers, i.e., those producing the coffee. Little money goes to production, cleaning, drying, and packaging. Transport and processing procedures performed in the industrialised countries, on the other hand, account for more than 80% of the price. Thus, value added, and consequently, possible economic growth takes place in the consumer, not the producer, countries.
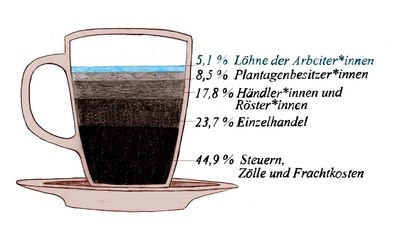
The coffee price
Many factors exert influence on the raw coffee price. On the one hand, supply and demand, in turn influenced by crop yields; on the other, stock exchange speculation on so-called paper coffee, as well as speculative hoarding and commodity futures, are driving prices down, which affects small-scale farmers in particular.
Increasing coffee world market prices - on the other hand - do not necessarily mean better prices for farmers. Big traders retain profit margins. During high-price periods, more coffee enters the world market; when prices drop, new contracts are concluded, and the coffee is stored, much like other financial transactions: the smaller the protagonist, the more likely financial losses. However, the more money there is in the background, the higher the probability of substantial gains. Therefore, bad harvests do not necessarily bring about better prices for farmers. Moreover, global supply can offset crop failures in single regions.
Yet it hasn't always been like that: Because of heavy price fluctuations and the resulting impoverishment of farmers, the International Coffee Organisation (IOC) concluded a coffee agreement between producer and consumer countries to regulate the coffee world market in 1962. The agreement imposed fixed quotas on all coffee-producing countries to avoid overproduction and price deterioration. After the Cold War, the US opted out of the agreement because its original purpose – to prevent impoverished farmers from joining the communist movement – had become obsolete. Ever since, every country can produce and export any quantity of coffee. As prices were no longer fixed, many small-scale farmers tended to produce more and more to compensate for per-unit losses. This, in turn, has reinforced overproduction. Additionally, more countries -supported by the World Bank - implemented coffee cultivation (e.g. Vietnam), resulting in a further surplus. As a result, coffee prices hit rock bottom. Farmers felt the low price's consequences intensely: in Ethiopia, a famine occurred; in Latin America, thousands had to abandon their land and live in slums in dire poverty. Child labour on coffee fields was increasing worldwide.[4]
Meanwhile, coffee prices have recovered. Yet the coffee business is still characterised by heavy price fluctuations, primarily to the producers' detriment.
Additionally, coffee has turned into an object of stock exchange speculation. Prices have therefore, to some extent, become independent of supply and demand and are becoming increasingly volatile. By contrast, smallholder farmers in particular need a framework that guarantees reliable sales. However, as they have very little influence over the world market, a new international coffee agreement appears unrealistic at present.'[5]
Value added in the Global North.
The refinement process of raw coffee and the consequent increase of the coffee price of about 1 euro per kilo up to 1000 euro per kilo for special coffees primarily takes place in rich industrialised countries like Germany. A substantial proportion of the coffee price covers taxes and marketing costs instead of benefiting farmers.
Besides the 7% value-added tax, Germany also charges a coffee tax of €2,19 per kilo of roasted coffee. This tax - socially unfair anyway due to not being proportional to income but a consumption tax – is not benefiting the production countries but Germany and the EU as economic locations and dominant players in world trade. Thus, global injustice is perpetuated and a huge proportion of value added stays in the North. Import tariffs also impede the development from raw material supplier to more sophisticated production chains and the establishment of more stable local economic structures.
Furthermore, European low-interest policy is exerting a negative influence. The ECB's depreciation and inflation strategy reflects a post-colonial logic of promoting exports, which will result in state debt vanishing into thin air due to inflation. This model relies on heavy price pressure and on keeping purchase prices of raw materials as low as possible compared to value added in the local economic sphere. Moreover, this development is reinforcing speculative bubbles and speculation in the financial market for paper coffee and other food.
Low-interest policy is promoting conventional trade in particular because currency fluctuations have a stronger impact on participants in fair or solidary trade. Higher consumer prices especially hurt poorer segments already concerned about rising rents; at the same time, low interest rates benefit well-off players investing in real estate. This is additionally tightening the market situation – a race to the bottom affecting all.
Coffee quality and roasting methods
Coffee trade and consumption are characterised by colonial history: Originally, it was cultivated for export and therefore for rich industrialised nations only. As a result, the best products are still exported today. On the other hand, coffee processing in importing countries is more complex. Expectations are substantially higher when it comes to coffee flavour, and numerous instructions must be followed regarding roasting, coffee machines, grinding, the heat of the water used for brewing, etc., before you can enjoy your drink. Many processing and refinement procedures are very sophisticated and, to some extent, even patented [6]. The considerable gourmet coffee sector also illustrates coffee expertise and the status of coffee as a luxury good.
Because taste is a top priority, roasting must be as fresh as possible. Consequently, producer countries often can't compete with industrialised nations' coffee culture and don't get the chance to export roasted coffee because long delivery and storage periods cause loss of quality and flavour, and markets are difficult to find. Therefore, it is not surprising that only 5% of roasted coffee is exported.[7]
These factors contribute to producer countries' difficulty accessing the European coffee market and to developing a role beyond mere raw coffee suppliers. Increased accessibility of small-scale players to logistics solutions and networks of solidarity, as well as improvement of infrastructure and local vocational training programs, are broadening local producers' options.
Monopolies
Coffee trade is dominated by five multinational trade and roasting companies.[8] Small-scale farmers' voice and influence on these corporations' pricing policy are negligible. Due to these monopolies, alternative price and trade structures can be realised in market niches only. Unorganised farmers remain in one-sided dependency. Even Fairtrade is merely a niche product; Fairtrade coffee's share in the market as a whole amounts to 4,4%.[9]
Naming the problem
Unfortunately, unequal and unfair trade relations are not the exception but the rule. Capitalist exploitation logic is defining the usual market mechanisms and is resulting in devastation of people and nature, misery and impoverishment. Armed conflicts and climate change are just the tip of the capitalist iceberg.
Equally, and unfortunately, as global market logic penetrates, we (Café Libertad) are also caught in this conflict. In practice, this means we negotiate prices as fairly as possible, but we don't exist in any utopian vacuum.
Paramount to us is questioning and fighting the capitalist system as a whole. Unfortunately, there is no sign of the system's immediate abolition. All too often, people and organisations are content with just a few political demands aimed at immediately improving producers’ circumstances. Such demands are being made by various groups and organisations (like Forum Fairer Handel (FFH)):
- * A ban on the import of resources and goods produced under less-than-minimum wage conditions.
- * Immediate stop of speculation on and stock exchange trade of food.
- * Companies' burden of proving their entire delivery chain complies with ecological and human rights standards. These agreements are to have legal prejudice over trade agreements (see FFH).
- In case of breach of the duty to exercise due care, concerned parties from abroad have to be able to sue German companies in German courts (see FFH).
- * 'European agricultural policy is to be supervised and has to be coherent with sustainable aims of development. There is regular monitoring of its consequences on markets in the South as well as complaint mechanisms for producers in developing countries.'[10]
Fairtrade was established to counter these exploitative structures rather than put forward demands. Unfortunately, the numerous labels and seals often contribute to confusion rather than clarifying the standards mentioned above.
[1] https://www.fairtrade-deutschland.de/produkte-de/kaffee/hintergrund-fairtrade-kaffee.html (29.01.2018)
[2] All Info: Deutscher Kaffeeverband https://www.kaffeeverband.de/de/kaffeewissen/handel#welthandel-fakten (29.01.2018)
[3] Statistisches Bundesamt von 2007: www.statsta.com. Illustration: Eva Müller, http://www.evamueller.org
[4] http://www.deutschlandfunkkultur.de/internationales-kaffeeabkommen-gescheiterte-hilfe.932.de.html?dram:article_id=273044 (29.01.2018). See also: Jean Ziegler (2005): Das Imperium der Schande.
[5] ibid.
[6] http://www.deutschlandradio.de/archiv/dlr/sendungen/patentes/179741/index.html (9.2.2018) regarding the complicated espresso-making process: http://www.spektrum.de/magazin/von-der-bohne-zum-espresso/829764
[7] https://www.kaffeeverband.de/de/kaffeewissen/handel#kaffeewissen-slider-78 (9.2.2018)
[8] 1. Nestlé 2. Mondelez 3.D.E.Master Blenders 4. Green Mountain 5 Tchibo. These statistics date from 2013. However, Mondelez and Douwe Egberts recently merged and became the new number 1 (headquartered in the Netherlands). In Germany, three suppliers are distributing 45% of the market among themselves: 1. Jacobs Douwe Egberts 2. Tchibo 3. Nestlé (in 5th place, there is Darboven, after Melitta)
https://de.statista.com/statistik/daten/studie/300720/umfrage/fuehrende-unternehmen-in-der-kaffeeherstellung-weltweit/ (29.01.2018)
[9] Forum Fairer Handel (2017): Aktuelle Entwicklungen im fairen Handel. https://www.faire-woche.de/fileadmin/user_upload/media/fairer_handel/zahlen_fakten/2017-07-20_aktuelle_entwicklungen_im_fh_2017.pdf (31.01.2018)
[10] http://www.forum-fairer-handel.de/politik/visionen-des-fh/ (29.1.2018)